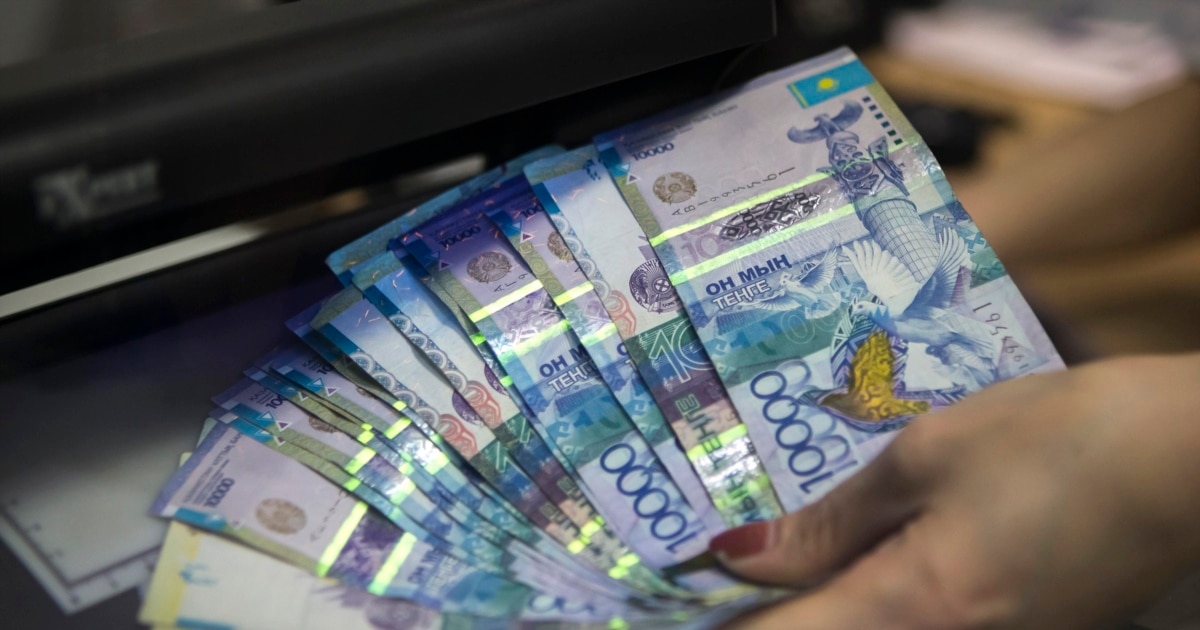
Kazakhstan Eases Banking Compliance Rules for Non‑Residents, Aiming to Reduce Barriers for Temporary Foreigners
Kazakhstan's financial regulator on September 7 approved changes to banks' internal control rules to simplify account and payment‑card issuance for foreigners temporarily in the country. Resolution No. 126, published on September 18, removes the automatic classification of non‑residents without residence permits as higher‑risk clients and eliminates several documentary and device checks, while maintaining standard anti‑money‑laundering obligations.
By Christopher Manley
1,132 views
Kazakhstan's financial regulator has loosened some compliance requirements for foreigners seeking to open bank accounts and obtain payment cards, a move authorities say is intended to reduce unnecessary administrative barriers for temporary residents such as migrant workers and visiting specialists. The Agency for Regulation and Development of the Financial Market (ARRFR) adopted the changes in Resolution No. 126 on September 7; the amendment was officially published on September 18.
Under the previous rules, non‑residents who lacked a residence permit or authorization for permanent residence were explicitly placed on a list of clients considered to present a higher risk for banks. That legal provision required financial institutions to apply enhanced scrutiny to such customers. The recent amendment removes the automatic presumption of higher risk solely on the basis of a missing residence permit.
Among the procedural relaxations introduced, banks will no longer be required to obtain a completed client questionnaire from these categories of foreign customers. Institutions also will not be obliged to verify the IMEI code of the customer's mobile phone as a condition for opening an account or issuing a payment card. The IMEI, a unique identifier assigned to mobile devices, had been part of verification routines under prior internal control practices.
The ARRFR emphasized that the changes represent an optimization of compliance procedures rather than an abolition of anti‑money‑laundering and counter‑terrorist financing controls. Financial institutions remain bound to conduct standard due diligence checks on customers and retain the authority to request additional documentation or information if transactions appear suspicious or indicate potential fraud. The agency said the amendments were made within the framework of rules aimed at countering the legalization (laundering) of proceeds from crime, financing of terrorism and the proliferation of weapons of mass destruction.
According to the regulator's statement, removing the blanket classification of non‑residents without residence permits as high‑risk clients should eliminate excessive administrative barriers faced by labor migrants, visiting professionals and other categories of temporary residents in Kazakhstan. By easing documentary burdens—while preserving core monitoring and suspicious‑activity reporting obligations—the ARRFR framed the reform as a balance between widening access to financial services and maintaining safeguards against illicit flows.
The change has practical implications for foreigners who rely on bank accounts and payment cards to receive wages, pay for services, manage remittances and participate in the formal economy. Easier account opening procedures can reduce reliance on cash and informal channels, potentially improving financial inclusion for temporary residents. At the same time, the regulator's insistence that banks continue standard checks indicates an awareness of the need to prevent regulatory gaps that could be exploited for money‑laundering or other financial crimes.
The ARRFR's amendment is a regulatory, not legislative, action: it updates banks' internal control rules that govern client identification and risk assessment. The new provision applies to banks and other financial institutions subject to these internal control regulations. The agency did not announce any specific additional safeguards or oversight measures in the published notice beyond reaffirming banks' ongoing obligations to investigate suspicious operations.
The resolution completes an administrative adjustment to the existing anti‑money‑laundering framework in Kazakhstan. By removing a categorical high‑risk designation for non‑residents without residence permits, authorities aim to streamline compliance burdens for temporary foreign customers while keeping in place the core mechanisms intended to detect and deter unlawful financial activity.